Key Takeaways
- Blue Owl owns 80% of Meta’s Hyperion campus; Meta owns 20%.
- A separate SPV raised $27B in A+ debt plus $2.5B equity — the largest private-credit deal on record.
- PIMCO holds $18B of the debt; BlackRock funds hold $3B.
- Our math: equity is 8.5% — the loss-absorbing cushion.
“Off balance sheet” doesn’t mean the debt vanished. It moved to a named SPV, held by named investors.
We covered the lease side of this story in September ($1.09T, not yet started). This piece covers a different mechanism: securitized debt with named buyers.
What Meta and Blue Owl Actually Signed
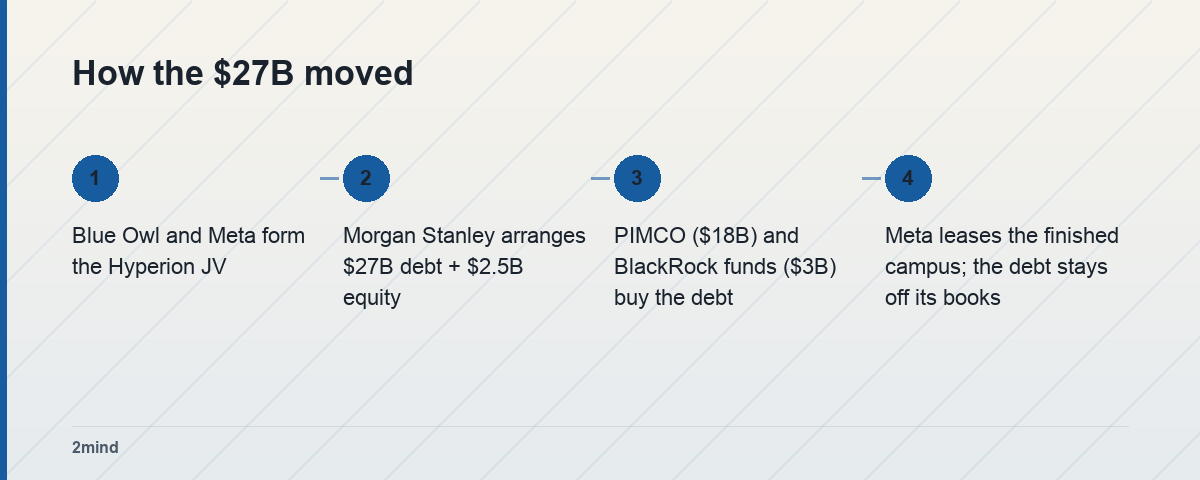
Meta’s October 2025 announcement describes a joint venture, not a loan. Blue Owl Capital funds develop and own 80% of the Hyperion campus in Richland Parish, Louisiana. Meta keeps 20%.
Blue Owl’s funds contributed roughly $7 billion cash to the JV. Meta received a one-time $3 billion distribution back out of it. Both sides fund their pro-rata share of the campus’s $27 billion development cost.
That $27 billion had to come from somewhere. Trade press coverage of the deal’s closing — not Meta’s own announcement — reports a separate financing package: $27 billion in A+-rated debt plus $2.5 billion in equity, arranged by Morgan Stanley.
PIMCO anchored the debt with an $18 billion purchase. BlackRock-managed funds, including several iShares ETFs, bought another $3 billion. The remaining roughly $6 billion went to other institutional bond buyers.
We could not fully reconcile Blue Owl’s $7 billion JV contribution against this later $27B+$2.5B package. Meta’s announcement says part of Blue Owl’s capital came from debt sold to PIMCO and other bond investors, but gives no figures for it. Both describe the same campus; we’re not merging them into one total.
The Capital Stack — Who Holds What
| Layer | Amount | Who holds it |
|---|---|---|
| JV equity (Blue Owl) | ~$7B contributed, owns 80% | Blue Owl Capital funds |
| JV equity (Meta) | 20% stake, $3B distributed out | Meta Platforms |
| SPV debt, A+ rated | $27B | PIMCO $18B, BlackRock funds $3B, others ~$6B |
| SPV equity | $2.5B | Not individually named in reporting |
Two “equity” lines appear because two transactions used the word. JV equity is who owns the campus. SPV equity is the buffer protecting the A+ debt rating — the number that decides who loses money first.
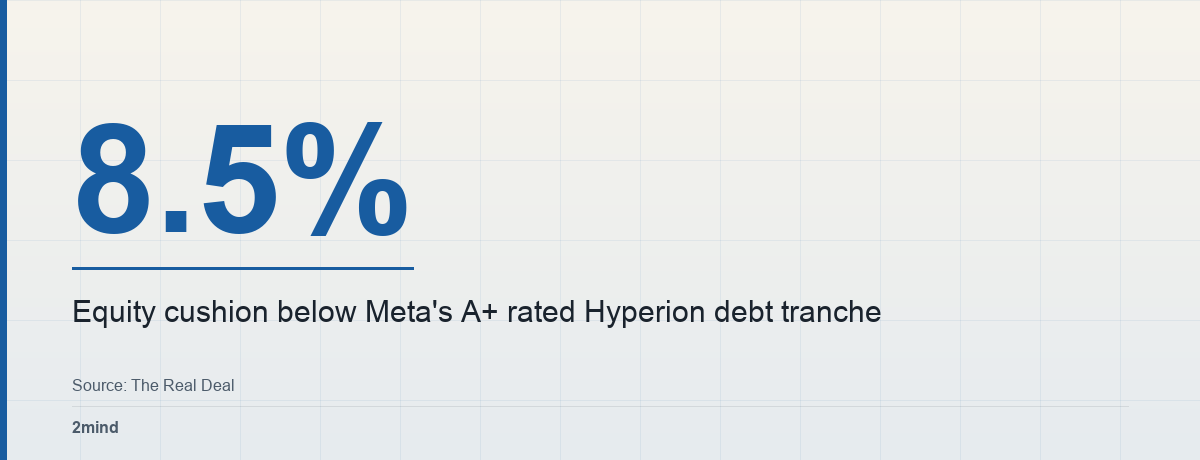
$2.5 billion of equity sits under $27 billion of debt — a 10.8-to-1 leverage ratio. Equity is 8.5% of the combined $29.5 billion package. Past that decline, A+ debt holders start absorbing losses too, unless Meta’s lease payments and its capped residual value guarantee step in.
None of our three source articles state that percentage; we calculated it from their two dollar figures.
Two Lenses
Building fast without the debt on your own books
Meta expands AI capacity without the SPV’s $27 billion showing up as its own debt. It leases the finished campus back under operating leases with a four-year initial term and renewal options instead. For a company already committing well over $100 billion a year to AI infrastructure, that keeps its reported leverage stable even as its AI footprint grows.
Someone’s retirement account is now underwriting a GPU bet
PIMCO and BlackRock don’t hold this debt with their own money. They hold it inside funds that pension plans and insurers put money into for steady, investment-grade-looking returns.
The Bank for International Settlements made a related warning in its March 2026 Quarterly Review. It calls these arrangements “shadow borrowing” that keeps most of the debt off the hyperscaler’s balance sheet.
By channelling private credit into AI infrastructure, it says, they “strengthen links between hyperscalers and non-bank investors such as private credit vehicles and insurers.”
We lean toward the second reading being underpriced. The A+ rating reflects Meta’s creditworthiness as eventual lessee, not an independent judgment on whether a single-tenant AI campus holds its value if demand cools. It has never been tested against a hyperscaler walking away from a data center lease.
What Would Change Our View
A similarly sized SPV with a visibly larger cushion — 20% or more — would suggest lenders are already pricing in AI-demand uncertainty.
If bond investors keep pushing back on pricing, as Forbes reported in July, and terms get less favorable to borrowers over the next two quarters, that would support the BIS’s systemic-risk framing over the “ordinary balance-sheet management” reading.
FAQ
Q. Is Meta’s Hyperion debt legally Meta’s debt?
A. No. It’s debt issued by a special purpose vehicle that owns the Hyperion campus, with Blue Owl’s funds and outside debt investors as counterparties. Meta leases the finished facility and reports that lease as an operating expense, not the SPV’s debt as its own liability.
Q. Who loses money first if an AI data center SPV like this underperforms?
A. The $2.5 billion equity tranche — roughly 8.5% of the $29.5 billion package, based on reported figures. Only after that cushion is gone would A+ debt holders like PIMCO and BlackRock-managed funds see losses, apart from Meta’s lease payments and capped residual value guarantee.
Q. How big is the AI data center financing gap industry-wide?
A. Morgan Stanley projects roughly $2.9 trillion in global data center capex through 2028, with hyperscaler cash flow covering about $1.4 trillion — leaving a $1.5 trillion gap it expects private credit, investment-grade bonds, and securitized credit to fill.
Sources
- Meta-Blue Owl Hyperion JV — Meta, Oct 2025
- Pimco’s $2B Hyperion windfall — The Real Deal
- Bridging a $1.5tr financing gap — Morgan Stanley
- BIS Bulletin 120, “Financing the AI boom: from cash flows to debt” — BIS, Jan 2026
- BIS Quarterly Review, “Financing the AI infrastructure boom: on- and off-balance sheet borrowing” — BIS, Mar 2026
- Bond investors push back on AI debt — Forbes, Jul 2026
Correction, October 2, 2026. An earlier version said the related lease story ran in August (it ran in September), dated BIS Bulletin 120 to June 2026 (it is dated January 2026) and attributed an off-balance-sheet warning to it (that warning is in BIS’s March 2026 Quarterly Review).
It also called an 8.5% equity cushion normal for commercial real estate debt, which we could not support, so the sentence was removed.
Leave a Reply