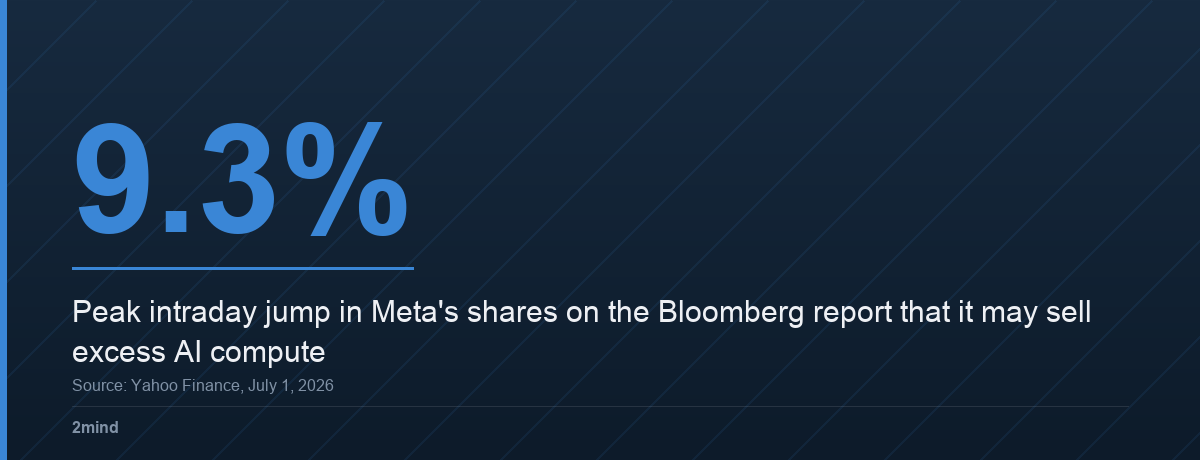
It is a strange signal when a company’s shares jump as much as 9% on a report that it may sell some of the computing it built.
Key Takeaways
- Meta shares rose as much as 9.3% after Bloomberg reported plans to sell excess AI computing capacity externally, following a model similar to SpaceX’s cloud approach.
- The move may reflect a build-out that has outrun internal AI demand, though Bloomberg’s report does not say so; the plan could also simply be a way to monetize spare capacity.
- This connects to a broader pattern in early July of AI infrastructure spending facing scrutiny over whether it can actually pay for itself.
What happened
| Company | Same-Day Stock Move (intraday, as reported) | Why |
|---|---|---|
| Meta | up as much as 9.3% | Reported plan to sell excess AI computing capacity |
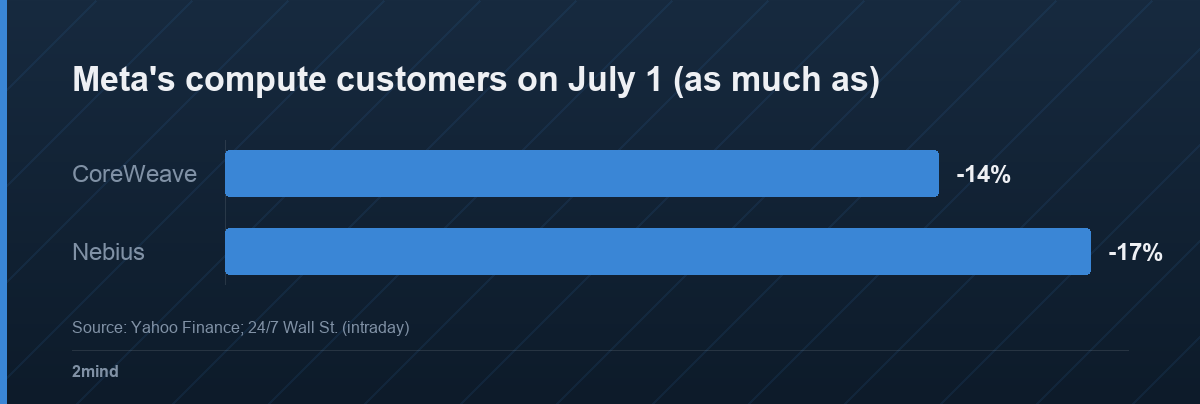
| CoreWeave | down as much as 14% | Risk of losing Meta as a compute customer |
| Nebius | down as much as 17% | Same risk |
On July 1, Meta shares jumped as much as 9.3% (closing up nearly 9%) after Bloomberg reported that the company is developing plans for a cloud computing business around its excess AI infrastructure; the plans were still in development, according to Yahoo Finance and CNBC.
Sizing the “excess capacity” claim against Meta’s own capex
Meta’s actual 2025 capital expenditure was $72.22 billion, according to its Q4/FY2025 earnings release. For 2026, Meta raised its guidance in April to a range of $125-145 billion (narrowed to $130-145 billion with its July 29 Q2 results) — up from an initial $115-135 billion forecast, per Yahoo Finance and Fortune reporting on the April 2026 earnings call. At the midpoint ($135 billion), that’s an 87% increase over 2025 spending; at the high end, it’s just over double.
| Year | Capex | Change vs. prior year |
|---|---|---|
| 2025 (actual) | $72.22B | — |
| 2026 (April guidance, low end) | $125B | +73% |
| 2026 (April guidance, high end) | $145B | +101% |
That trend matters for reading the “excess capacity” announcement correctly: even a low single-digit percentage of a $125-145 billion 2026 build sitting underused is billions of dollars of idle GPU capacity — enough to make selling it externally a rational capital-allocation move on its own, independent of whether Meta’s internal AI demand is falling short. The scale of the buildout, not just the demand shortfall, is why this decision is happening now.
The approach mirrors what SpaceX has done by selling GPU capacity from its xAI Colossus data centers — rather than letting expensive GPU clusters sit underutilized, Meta intends to sell that computing power externally, alongside offering its AI models as a direct service.
Some observers speculate the plan reflects internal AI products not yet generating demand strong enough to justify the infrastructure already committed; Bloomberg’s report does not say so.
This lands amid a week where AI infrastructure economics have come under closer examination more broadly. Palantir CEO Alex Karp separately criticized the “token-based” pricing model used by companies like OpenAI and Anthropic, arguing that enterprises are paying heavily for API access while handing over valuable data without getting proportional value in return.
Meanwhile, Nvidia unveiled a new continual-learning robotics system called Aspire, designed to let robots write and debug their own control code — a sign that infrastructure providers are still pushing hard on new AI applications even as demand questions swirl around existing ones.
Why CoreWeave and Nebius fell harder than Meta rose
A jump of as much as 9.3% for Meta against drops of as much as 14% and 17% for CoreWeave and Nebius on the same day isn’t a symmetric market reaction. Investors read this less as “Meta found a smart use for spare capacity” and more as a direct competitive threat.
That asymmetry is itself a data point. Markets rewarding Meta more modestly than they punished its GPU cloud partners implies genuine uncertainty about how large a threat Meta’s move actually represents, not universal enthusiasm for the pivot.
CoreWeave and Nebius built their businesses partly on the assumption that hyperscalers like Meta would keep buying rather than building enough capacity to compete. This announcement tests that assumption directly, in public, on a single trading day.
The two lenses
Lens one: the pragmatic monetization case. Under this reading, Meta is doing exactly what any capital-intensive infrastructure operator should do — treating spare capacity as an asset rather than a sunk cost.
Data centers and GPU clusters are enormously expensive to build and maintain; if internal workloads don’t use 100% of that capacity around the clock, renting it out is simply smart capital allocation.
Cloud providers like AWS and Azure built entire empires on exactly this principle: sell compute as a service, let demand from many customers smooth out utilization. Under this view, the market’s positive reaction reflects investors rewarding capital discipline, not punishing Meta for a strategic misstep.
Lens two: the demand-shortfall warning. Under this reading, the timing matters more than the mechanism. Companies don’t typically pivot into selling infrastructure externally unless their own use case has fallen short of projections.
Meta has poured tens of billions into AI infrastructure over the past two years on the premise that its own products — recommendation engines, Llama models, advertising tools — would consume that capacity. If that’s not happening fast enough, opening a cloud business is as much a hedge against overbuilding as it is an opportunity.
This reading treats the stock jump less as celebration of a smart pivot and more as relief that management found a use for capacity that might otherwise sit idle.
The market’s reaction to Meta wasn’t universal, either — GPU cloud specialists CoreWeave and Nebius, both major Meta compute customers, fell as much as 14% and 17% respectively the same day, as investors weighed the risk of their biggest client becoming a direct competitor.
What Karp’s criticism adds to this story
Palantir CEO Alex Karp’s complaint about token-based pricing lands on a related but separate problem: even companies not overbuilding infrastructure are questioning whether they get proportional value from what they pay AI vendors for API access.
Put together with Meta’s capacity announcement, that stretch’s news read less like one company’s story and more like an industry-wide reckoning with how AI gets priced and paid for at every layer of the stack.
It’s worth noting Karp runs a company with its own stake in how enterprises spend AI budgets, so his framing isn’t disinterested. Still, the underlying complaint — that paying per token doesn’t guarantee proportional value — is one worth separating from who happens to be voicing it.
Why it matters
For investors, this is a signal worth tracking across the whole hyperscaler cohort, not just Meta — if internal AI demand is falling short of infrastructure buildout even at a company with Meta’s user base and ad business, it raises the question of whether the entire sector’s capex assumptions need revisiting.
For enterprise AI buyers, Karp’s criticism of token-based pricing adds a separate but related thread: the economics of consuming AI services, not just building them, are under fresh scrutiny.
Watch whether other hyperscalers follow with similar external monetization plans, and whether Meta’s later earnings calls show whether this cloud pivot is generating meaningful revenue or is still an early-stage experiment.
The infrastructure boom hasn’t stopped, but the free ride on faith alone may be ending.
What Nvidia’s Aspire announcement quietly signals
Infrastructure providers unveiling new applications — like Nvidia’s Aspire robotics system — in the same stretch that demand questions swirl around existing AI products is worth noting. It suggests the industry’s answer to soft demand in one area is more product surface area, not less spending.
Whether that surface area translates into revenue Meta can point to, separate from its core advertising business, is a different question than whether the technology itself works. Both things can be true — the tech works, and the market for it is still unproven.
FAQ
Q. Why is Meta selling its AI computing capacity?
A. Bloomberg reported that Meta is developing plans to sell excess AI computing capacity; the plan was still in development and Meta did not comment. Whether weak internal demand is the reason is speculation, since the plan may simply reflect the scale of the build-out.
Q. Is this similar to what other tech companies have done?
A. Yes, the approach resembles SpaceX’s model of monetizing excess capacity,
What would change our view
If Meta’s later earnings show its cloud pivot generating meaningful, growing external revenue rather than a one-time announcement, the pragmatic-monetization reading in Lens one gains real support.
It would also change if Meta’s own AI products show a sharp jump in internal compute demand in coming quarters, undercutting the idea that this move was driven by a shortfall rather than opportunism.
Sources
- [Meta Jumps 9.3% on Plans for AI Cloud Infrastructure Business] — Yahoo Finance
- [Meta Reports Fourth Quarter and Full Year 2025 Results] — Meta Investor Relations
- [Meta just bumped its 2026 capex forecast up to as much as $145 billion] — Fortune
- [Meta pops 9% as company makes cloud push to sell excess AI compute power capacity] — CNBC, July 1, 2026
- [Nebius, Coreweave, and IREN Tumble on Meta’s Cloud Ambitions] — 24/7 Wall St., July 1, 2026
- [Palantir CEO criticises OpenAI, Anthropic’s token-based AI pricing] — Business Standard, July 2, 2026
- [ASPIRE: Agentic Skills Discovery for Robotics] — NVIDIA Research
Correction, October 2, 2026. An earlier version dated Meta’s share jump to July 2 and said Meta announced the plan; the move was on July 1 after a Bloomberg report, and Meta did not comment.
It compared the plan to SpaceX selling Starlink’s spare capacity, but SpaceX sold GPU capacity from its xAI Colossus data centers.
It said Meta raised 2026 capital expenditure guidance twice; it was raised once in April and narrowed on July 29.
Leave a Reply